We all know that moment. You try to rent your first apartment, finance a phone or sign up for a utility, and the screen says “insufficient credit history.” You have never missed a payment in your life, because you have never had anything to pay. That is the catch with credit: you need credit to get credit.
Your first credit card is the way out of that loop. Pick the right one and you will have a FICO score in about six months and a better card offer in about a year.
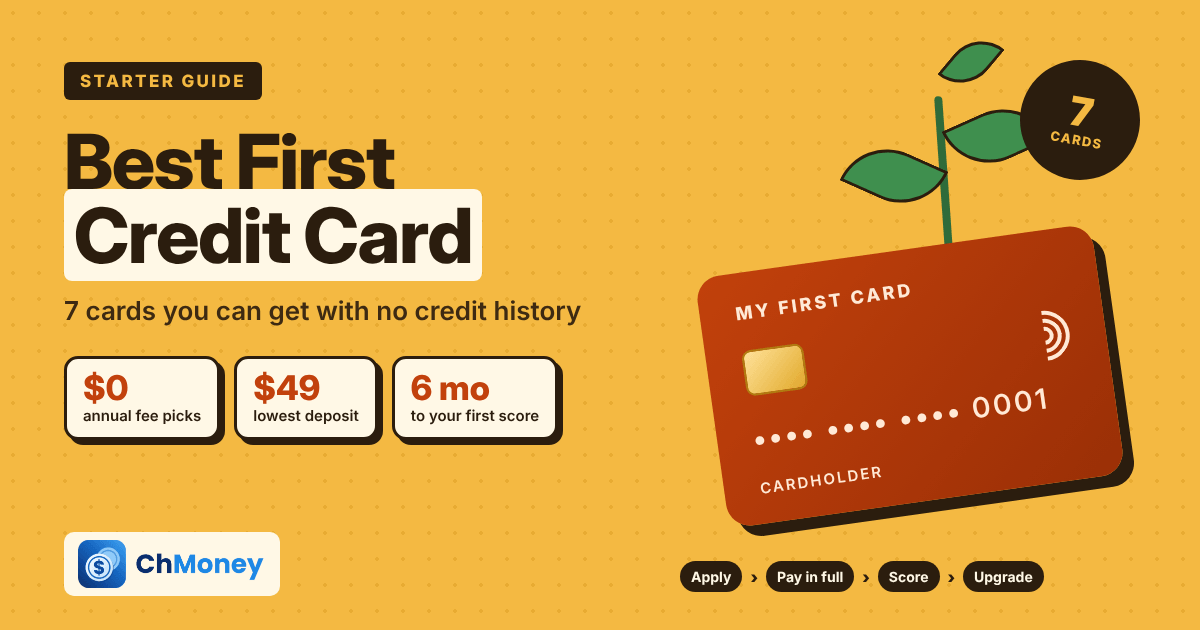
The short answer: the best first credit card for most people is a $0 annual fee secured card from a big bank, like the Discover it Secured or the Capital One Platinum Secured, or a student card if you are in college. Use it for one small bill, pay it in full every month, and expect your first FICO score around month six.
The rest of this guide gives you seven cards a true beginner can get approved for, what each one costs in dollars, and a month-by-month plan to go from zero to a regular unsecured card.
What is the best first credit card?
The best first credit card is one you can get approved for with no credit history, that charges no annual fee, and that reports to all three credit bureaus. For most beginners that means the Discover it Secured ($200 deposit, cash back) or the Capital One Platinum Secured (deposit as low as $49).
Here are seven cards built for people starting from zero. All figures come from the issuers’ own pages, checked November 14, 2026.
| Card | Best for | Deposit | Annual fee | Purchase APR | Rewards | Upgrade review |
|---|---|---|---|---|---|---|
| Discover it Secured | Most beginners | $200 minimum, up to $2,500 | $0 | 22.99% variable | 2% at gas stations and restaurants (up to $1,000 a quarter), 1% everything else | Automatic monthly reviews starting at 8 months |
| Capital One Platinum Secured | Lowest deposit | $49, $99 or $200 for a $200 limit | $0 | 29.24% variable | None | No set timeline; line increases based on payment history |
| Capital One Platinum | No deposit, limited credit | None | $0 | 29.24% variable | None | Considered for a higher limit in as little as 6 months |
| Discover it Student Cash Back | College students | None | $0 | 16.74% to 25.74% variable (0% intro for 6 months on purchases) | 5% on rotating quarterly categories when you activate, 1% everything else | N/A, already unsecured |
| Chime Card (formerly Chime Credit Builder) | No credit check at all | No minimum; you move money in from Chime Checking | $0 | No interest | Cash back tied to Chime direct deposit status | N/A |
| BankAmericard Secured | You already bank at Bank of America | $200 minimum, up to $5,000 | $0 | 26.24% variable | None | Periodic reviews (check with the bank) |
| Petal 2 Visa | Steady income, no credit score | None | $0 | 28.24% to 30.24% variable | 1% to 1.5% cash back, more at select merchants | N/A, already unsecured |
A quick word on why some popular cards are missing. Chase Sapphire Preferred, Chase Freedom Flex and Wells Fargo Active Cash show up on a lot of “first credit card” lists. They are good cards, but Bankrate says the Active Cash suits a FICO score of 670 or higher, and the Sapphire Preferred asks you to spend $5,000 in three months for its bonus. If you have no credit file, you will most likely get declined, and that decline still puts a hard inquiry on your report.
Which first card fits your situation?
Match the card to where you are starting. Students should start with a student card. People with no credit and no school ID should start with a secured card. If you can’t put down a deposit, look at Capital One Platinum or a card that checks your bank account instead of your credit.
- You have no credit, but you can set aside $200: Discover it Secured. You get cash back, no annual fee, and Discover starts checking at month eight if you can move to an unsecured card and get your deposit back.
- You can only spare $49 to $99: Capital One Platinum Secured. Depending on your application, a $49 or $99 deposit still gets you a $200 limit.
- You are in college: Discover it Student Cash Back. Discover says no credit score is required to apply, but you need to be 18, show income and show you are enrolled.
- You can’t come up with any deposit: try Capital One Platinum, which Capital One labels for “fair” credit and limited history. Use its prequalification tool first; Capital One says checking has no impact on your credit score.
- You want zero chance of interest or a credit check: Chime Card. It has no annual fee, no interest and no credit check, but you need a Chime Checking account and you can only spend the money you move in.
- You already have a checking account at a big bank: apply there first. Your bank can see your deposits and balance history, which gives them something to go on when your credit file is empty. Bank of America’s BankAmericard Secured is one example.
- A parent has good credit and will add you: ask to be an authorized user on their oldest card. More on that below.
If you just moved to the US or your credit is thin, cards like the Petal 2 look at your bank account cash flow instead of a credit score. You still need steady income going into a checking account.
Can you get a credit card with no credit history?
Yes. Secured cards, student cards and a few starter cards from Capital One are made for people with no credit file. A secured card is the easiest because your deposit covers the bank’s risk, so approval depends mostly on income and identity, not on a credit score.
Having no credit is different from having bad credit. No credit means the bureaus don’t have enough data to score you. The CFPB estimates that 2.7% of US adults were “credit invisible” in 2020, meaning they had no credit file at all. Millions more have a file that is too thin to score.
Here is how the three types of starter cards compare:
| Type | How it works | Good | Watch out for |
|---|---|---|---|
| Secured card | You pay a refundable deposit, and it usually sets your limit | Easiest approval, deposit comes back when you upgrade or close in good standing | Money tied up, low limit makes utilization tricky |
| Student card | Unsecured card for enrolled students with some income | No deposit, often has rewards | Needs proof of enrollment and income |
| Unsecured starter card | Regular card with a low limit for limited credit | No deposit | Higher APRs (29.24% on Capital One Platinum), easier to get declined |
How old do you have to be to get a credit card?
You have to be 18 to open your own credit card. If you are under 21, the Credit CARD Act of 2009 says you need either your own independent income that can cover the payments or a co-signer who is 21 or older. Allowance or a parent’s income doesn’t count.
Part-time job income, scholarship money paid to you for living costs and regular freelance income all count as independent income. Write the real yearly number on the application. Lying about income on a credit application is a federal crime, and the issuer can ask for proof.
Many big issuers no longer accept co-signers. If you are under 21 with no income, your best move is to become an authorized user on a parent’s card until you have a job.
How long does it take to get a credit score?
You need about six months. A FICO score needs at least one account that has been open six months or more and at least one account reported to a credit bureau in the last six months. So if you open your first card in January, expect your first FICO score around July.
That rule comes straight from myFICO’s own requirements. Some free credit apps show a VantageScore, which uses different rules, so you may see a number there earlier. Lenders use FICO most of the time, so the six-month mark is the one to plan around.
Don’t apply for more cards in those first six months hoping it will speed things up. It won’t. Each application is a hard inquiry that stays on your report for two years, and FICO counts it for one year.
How to build credit with your first card, month by month
Use the card for one small bill, set autopay for the full statement balance, keep the balance under 10% of your limit when the statement closes, and leave the card open. That routine gets most people a FICO score at month six and an upgrade review by month eight to twelve.
- Month 0: Apply for one card. Use the issuer’s prequalification tool first if it has one. Capital One, Discover and Bank of America all offer one, and it doesn’t touch your score.
- Month 1: Put one bill on it. A phone bill, a streaming service or a tank of gas. Something small and the same every month.
- Month 1: Turn on autopay for the full statement balance. Payment history is 35% of your FICO score. One payment 30 days late can stay on your report for seven years.
- Months 1 to 6: Watch the statement date, not only the due date. The balance on your statement is what gets reported. Pay it down before the statement closes to report a low balance. Our guide on when to pay your credit card to avoid interest (link) shows how the two dates work.
- Month 6: Check your score. Many card apps, including Discover’s and Capital One’s, show a free score. You can pull your reports for free at AnnualCreditReport.com.
- Month 8: Look for the upgrade. Discover runs automatic monthly reviews starting at month eight on the Discover it Secured. Capital One considers Platinum cardholders for a higher limit in as little as six months.
- Month 12: Think about card number two. After a year of on-time payments you can usually qualify for a regular no-fee cash back card. Our guide on how many credit cards you should have (link) walks through when a second card helps.
How much of your credit limit should you use?
Keep the balance that shows on your statement under 30% of your limit, and under 10% if you can. On a $200 limit that means under $60, or $20 for the best results. Amounts owed, which is mostly utilization, makes up about 30% of your FICO score, so a maxed-out card hurts even when you pay on time.
Small limits make this tricky. One grocery run can push you over. Here is what the numbers look like:
| Credit limit | 30% of limit | 10% of limit |
|---|---|---|
| $200 | $60 | $20 |
| $500 | $150 | $50 |
| $1,000 | $300 | $100 |
| $2,500 | $750 | $250 |
Say your limit is $200 and you spend $150 in a month. If your statement closes with $150 on it, the bureaus see 75% utilization. Pay $130 a few days before the statement date and they see $20, or 10%. You paid the same total, but your score sees a very different card.
This is also why a bigger deposit on a secured card can be worth it. Putting $500 down instead of $200 gives you more room before you cross 30%.
What does a 29% APR cost you?
If you pay your full statement balance every month, the APR costs you nothing because you keep your grace period. If you carry a balance, a 29.24% APR on $500 costs about $12 a month in interest. The Federal Reserve’s average for accounts paying interest was 22.36% in the third quarter of 2026.
Starter cards charge more than average. Capital One Platinum and Platinum Secured sit at 29.24%. Discover it Secured is 22.99%. The Fed’s G.19 release from November 6, 2026 puts the average at 21.19% for all card accounts and 22.36% for accounts that actually got charged interest.
Here is the math on carrying $500 for a month:
| APR | Monthly interest on $500 |
|---|---|
| 22.36% (Fed average for accounts paying interest) | about $9.32 |
| 22.99% (Discover it Secured) | about $9.58 |
| 29.24% (Capital One Platinum) | about $12.18 |
Twelve dollars doesn’t sound like much. But if you only pay the minimum, that balance can hang around for years and the interest adds up every month. The simple rule for a first card: never charge more than you already have in your checking account.
Are annual fees worth it on a first card?
Almost never. Every card in the picks table above charges $0. A $39 annual fee card like the Capital One QuicksilverOne needs $2,600 a year in spending at 1.5% cash back just to break even. Cards with $75 to $125 fees and 35% APRs cost more than a beginner will ever earn back.
Some starter cards aimed at people with no credit or bad credit charge fees in the first year, monthly maintenance fees, or both. Surge Platinum Mastercard, for example, lists $75 to $125 a year and a 35.90% APR. Our Destiny credit card review (link) breaks down a card with $75 to $250 in first-year fees and a 35.9% APR. Read it before you sign up for anything with a fee.
The $0 secured cards give you the same credit building for free. The only thing you pay is the deposit, and you get that back.
How do you graduate from a secured card?
Make every payment on time, keep your balance low, and update your income with the issuer when it goes up. Discover reviews Discover it Secured accounts automatically each month starting at month eight. If you qualify, it switches you to an unsecured card and refunds your deposit, and the account keeps its age.
Capital One doesn’t give a set timeline for Platinum Secured. Its page says you could earn back your deposit and upgrade to an unsecured card based on your payment history. If you hit a year of on-time payments and nothing happens, call and ask.
Two things to avoid. First, don’t close the secured card to get your deposit back if the issuer offers an upgrade instead. Closing it shortens your credit history. Second, don’t miss a payment in the months before a review. One late payment can reset the clock.
What if you get denied?
Ask why. The issuer has to send you a letter, called an adverse action notice, with the reasons. Then wait a few months before the next application and try a route that doesn’t depend on your credit file, like an authorized user spot, a credit-builder loan or a card with no credit check.
| Option | How it builds credit | Cost | Credit check |
|---|---|---|---|
| Authorized user on a parent’s card | Their account history can show on your report | Free | No |
| Credit-builder loan (credit unions, online lenders) | You make fixed payments into savings; payments get reported | Small interest or fees | Usually soft or none |
| Co-signed card | You share the account and the history | Free, but the co-signer owes the debt too | Yes, on both of you |
| No-credit-check secured card (Chime Card, OpenSky) | Reports like a regular card | $0 for Chime Card; check fees on others | No |
| Store card | Reports like a regular card | High APRs, often 30% or more | Yes, but easier approval |
The authorized user route works only if the main cardholder pays on time and keeps balances low. Their mistakes land on your report too. Ask them to add you to their oldest card with the cleanest history.
First credit card mistakes to avoid
The biggest mistakes are paying only the minimum, using most of your limit, missing a payment, applying for several cards at once and closing your first card. Any one of those can cost you points that take months to win back.
- Paying only the minimum. You’ll pay interest on everything left over, at 22% to 29% a year.
- Maxing out the card. Even if you pay in full, a high statement balance shows up as high utilization.
- Applying for three cards in a month. Three hard inquiries and three new accounts make lenders nervous.
- Picking a card for the bonus. A $95 travel card with a $5,000 spend requirement isn’t a starter card.
- Closing your first card. That account is your oldest one. Keep it open and use it once every few months so the issuer doesn’t close it.
- Using a debit card and thinking it builds credit. Debit cards don’t report to credit bureaus. Only credit accounts do.
Frequently asked questions
What is the easiest first credit card to get? A secured card is the easiest because your deposit covers the bank. Chime Card has no credit check at all, but you need a Chime Checking account. Capital One Platinum Secured accepts deposits as low as $49.
Can I get a credit card with no job? If you are 21 or older, you can count income you can reasonably reach, like a spouse’s income. If you are under 21, you need your own independent income or a co-signer who is 21 or older.
Does a secured card build credit as fast as a regular card? Yes. Discover, Capital One and Bank of America report secured cards to the credit bureaus the same way as regular cards. FICO scores treat a secured card like any other credit card.
How much should my first credit limit be? Most first cards start between $200 and $1,000. A secured card limit usually equals your deposit, so Discover it Secured starts at $200 and goes up to $2,500 if you deposit more.
Should my first credit card have rewards? Rewards are nice but they shouldn’t decide it. Pick a $0 fee card you can get approved for. Discover it Secured gives 2% at gas stations and restaurants, so you don’t have to give up rewards to start.
How many credit cards should I get at first? One. Wait at least six months to a year of on-time payments before you apply for a second card.
Can I use a debit card to build credit? No. Debit card activity doesn’t go to the credit bureaus. You need a credit account, like a credit card or a credit-builder loan.
How long until I can get a better card? Usually 6 to 12 months of on-time payments. You need six months just to get a FICO score, and most issuers want to see a few more months of clean history after that.
The best first credit card is a boring one: no annual fee, easy approval, reports to all three bureaus. For most people that is the Discover it Secured or the Capital One Platinum Secured, or the Discover it Student Cash Back if you are in school. Put one small bill on it, autopay the full balance, keep the statement balance under 10% and leave the card open. In six months you’ll have a FICO score. In about a year you’ll have better offers coming to you.